


Financial Supply Chain Management
Sustainable Trade Finance
Sustainability Report

-
you are in Wholesale Banking

For Individuals
Personal BankingWealth BankingPrivilege BankingFor Companies
Wholesale BankingINDUSTRY INSIGHTSAbout UOB
ABOUT USUOB FinLaB
UOB FinLab

Overview
A Call Spread Option is a structured foreign exchange hedging solution that combines the purchase and sale of two FX options with the same maturity but different strike rates. It helps manage foreign exchange risk while potentially reducing the upfront premium compared to purchasing a standalone FX option.Benefits
Cost efficiency
Potentially lower upfront premium.
Downside protection
Obtain protection against exchange rate risk within a certain range.
Limited upside participation
Benefit from favourable FX moves within a set range.
Flexible structuring
Tailored to Customer’s specific hedging objectives.
Competitive pricing
Access competitive market-based pricing.
Treasury expertise
Benefit from UOB Indonesia's treasury expertise.
Features
-
Key Features
-
Details
| Key Features | Details |
| Available Currencies | Available for selected foreign currencies, including AUD, CAD, CNH, EUR, GBP, HKD, IDR, JPY, NZD, SEK, SGD, and USD, subject to prevailing market conditions and the Bank’s approval. |
| Flexible Tenor | Available with a tenor up to 5 (five) years, subject to applicable regulations and the Bank’s approval. |
| Two-Option Structure | Combines the purchase of one FX option and the sale of another FX option with different strike rates but the same maturity date. |
| Premium Optimisation | The premium received from the sold option may partially offset the premium paid for the purchased option. |
| Defined Protection Range | Provides protection against adverse exchange rate movements within a pre-agreed range while maintaining the opportunity to benefit from favourable market movement. |
| Customisable Terms | Currency pair, strike rates, notional amount and maturity can be tailored to suit specific hedging requirements, subject to the Bank’s approval and prevailing market conditions. |
| Dynamic Hedging Feature | Customers may choose to establish a new Call Spread Option as market conditions change, allowing the hedging strategy to be adjusted by creating a new protection range. |
| Transaction Requirements | • Have an FX and Derivative Limit facility with the Bank. • Having an account with the Bank. • Sign agreement and/or other documents required by the Bank. • Qualifying as a Professional Customer in accordance with applicable regulations. • Completing the Bank’s suitability assessment and having an appropriate risk profile for the product. • Provide transaction underlying and transaction supporting document. |
| Key Features |
| Available Currencies |
| Flexible Tenor |
| Two-Option Structure |
| Premium Optimisation |
| Defined Protection Range |
| Customisable Terms |
| Dynamic Hedging Feature |
| Transaction Requirements |
Product risk
-
Risks
-
Details
| Risks | Details |
| Market Risk | Changes in market exchange rates, interest rates, and market volatility may affect the market value of the Call Spread Option during its tenor. |
| Credit Risk | Risk that arises if the Bank is unable to fulfil its contractual obligations under the Call Spread Option transaction, which may affect settlement of the transaction. |
| Liquidity Risk | Early termination, cancellation, or unwinding of the Call Spread Option before maturity may be subject to prevailing market liquidity and pricing. This may result in costs or a gain or loss depending on market conditions at the time of termination. |
| Compliance Risk | Changes in applicable laws and regulations, including amendments to provisions and policies issued by the Government, Bank Indonesia and/ or the Financial Services Authority (OJK), may affect the availability, terms, execution, or settlement of the Call Spread Option transaction. |
| Risks |
| Market Risk |
| Credit Risk |
| Liquidity Risk |
| Compliance Risk |
Scenario
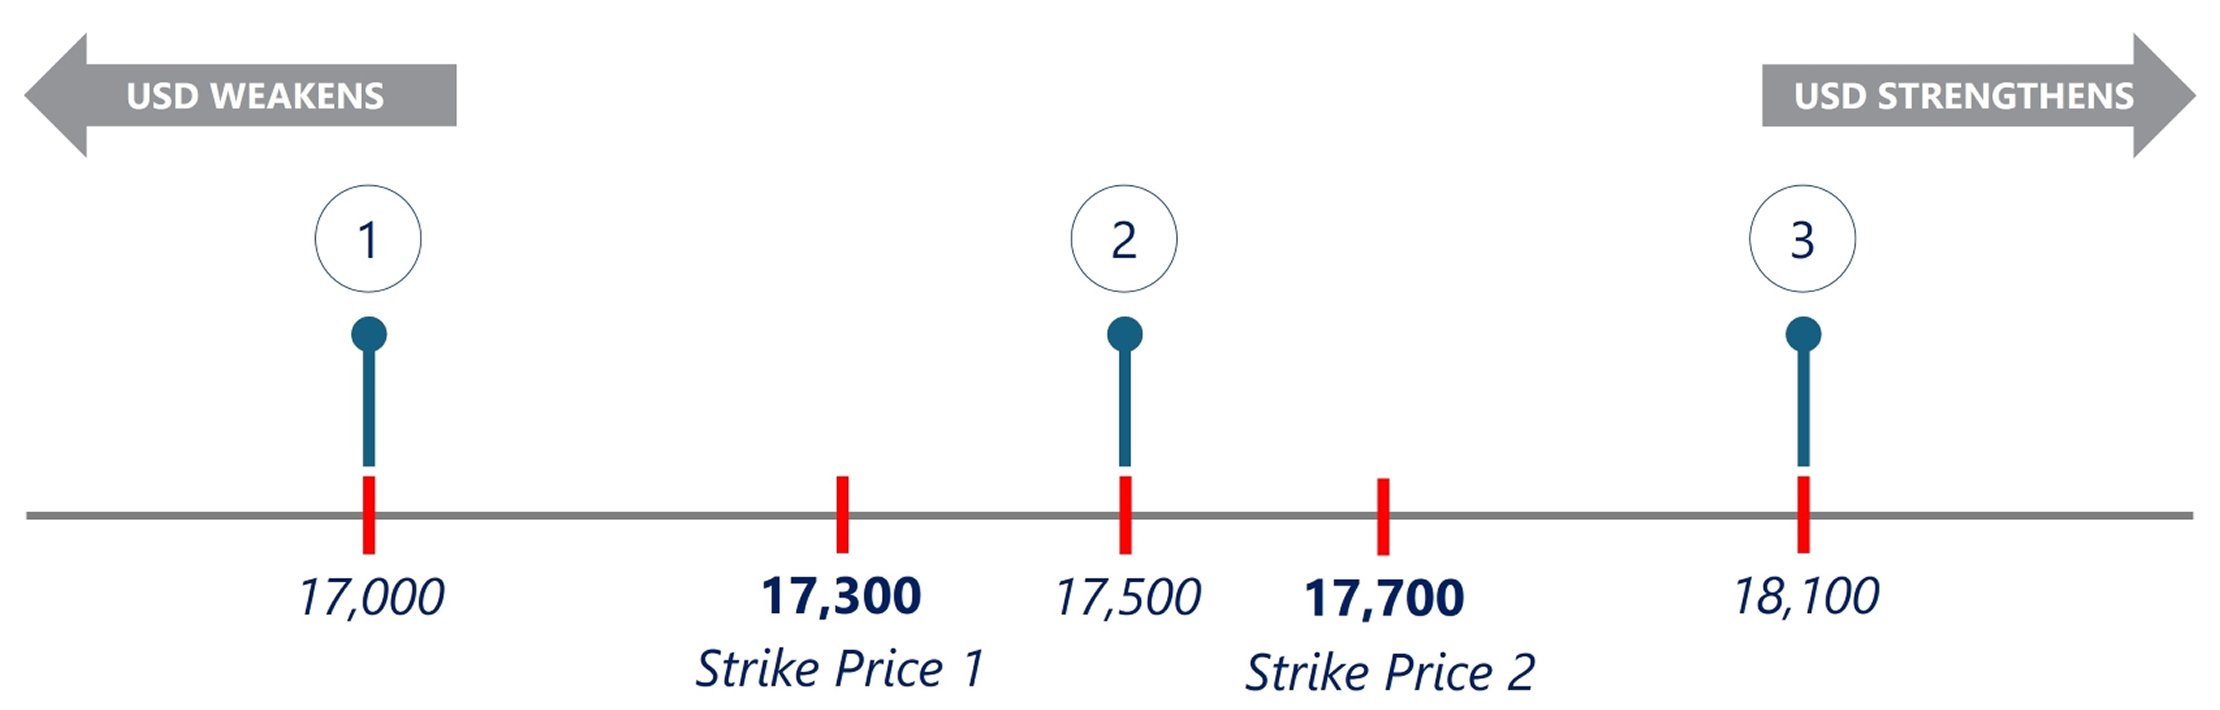
A company expects to purchase USD 1,000,000 in three months and wishes to manage the risk of a strengthening USD while reducing the upfront premium compared to purchasing a standalone FX Option.- Buy USD Call Option at Strike Price 1 USD/IDR 17,300
- Sell USD Call Option at Strike Price 2 USD/IDR 17,700
- Tenor: 3 months
- Premium: 0.30% of the transaction notional
- Same expiry date
- Both the purchased and sold USD Call Options are exercised and settled through full movement of funds (not on a net settlement basis).
- The company purchases USD at the lower strike rate of 17,300 and sells USD at the upper strike of 17,700, receiving the difference between the two strike rates. The company subsequently purchases USD at the prevailing market exchange rate to fulfil its underlying foreign exchange requirement.
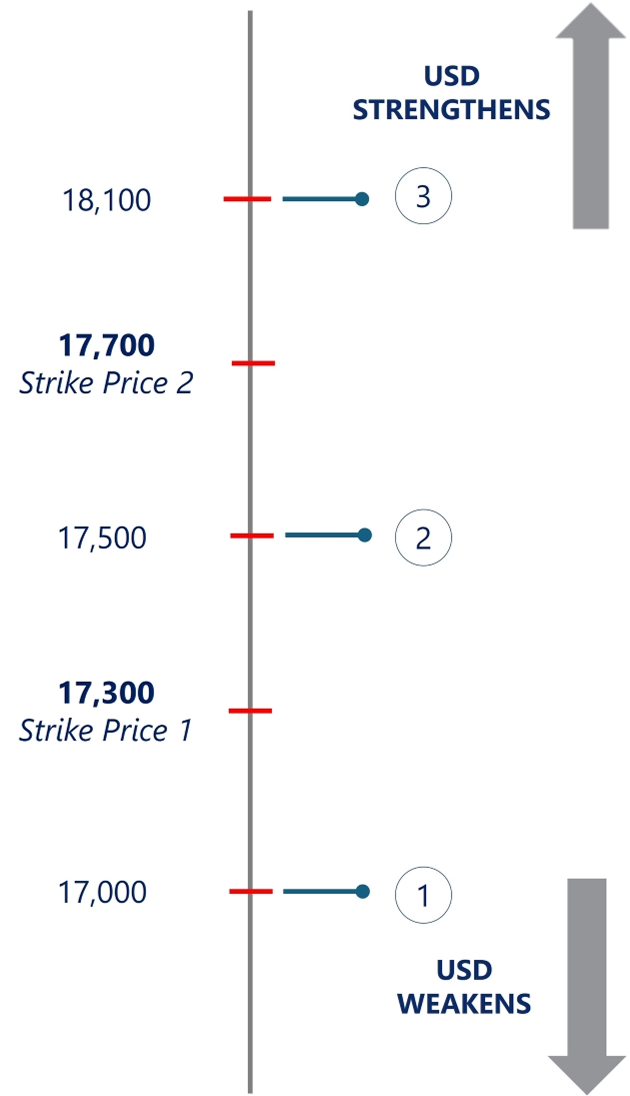
Dynamic Hedging Scenario
Assume that before expiry, the USD/IDR exchange rate increases above 17,700.- Buying a new USD Call Option at Strike Price 3 USD/IDR 17,700.
- Selling a new USD Call Option at a higher strike (for example Strike Price 4 USD/IDR 18,100), subject to prevailing market conditions.
- Paying a new premium for the new Call Spread Option, determined based on prevailing market conditions at the time the new transaction is entered into.
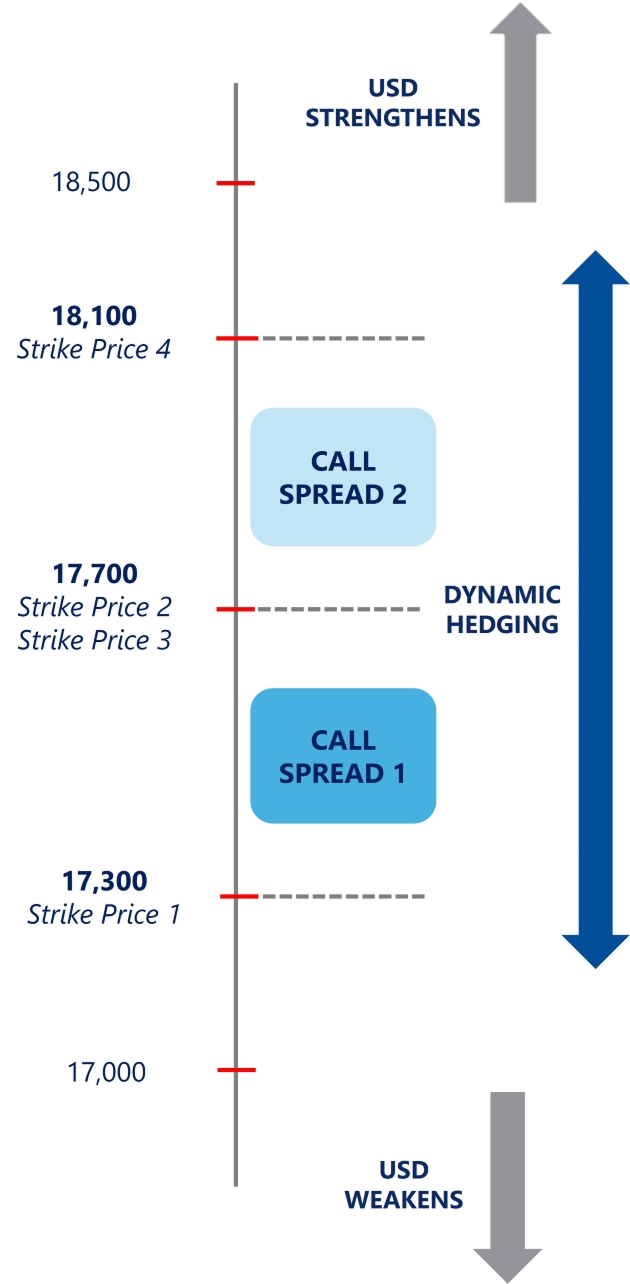
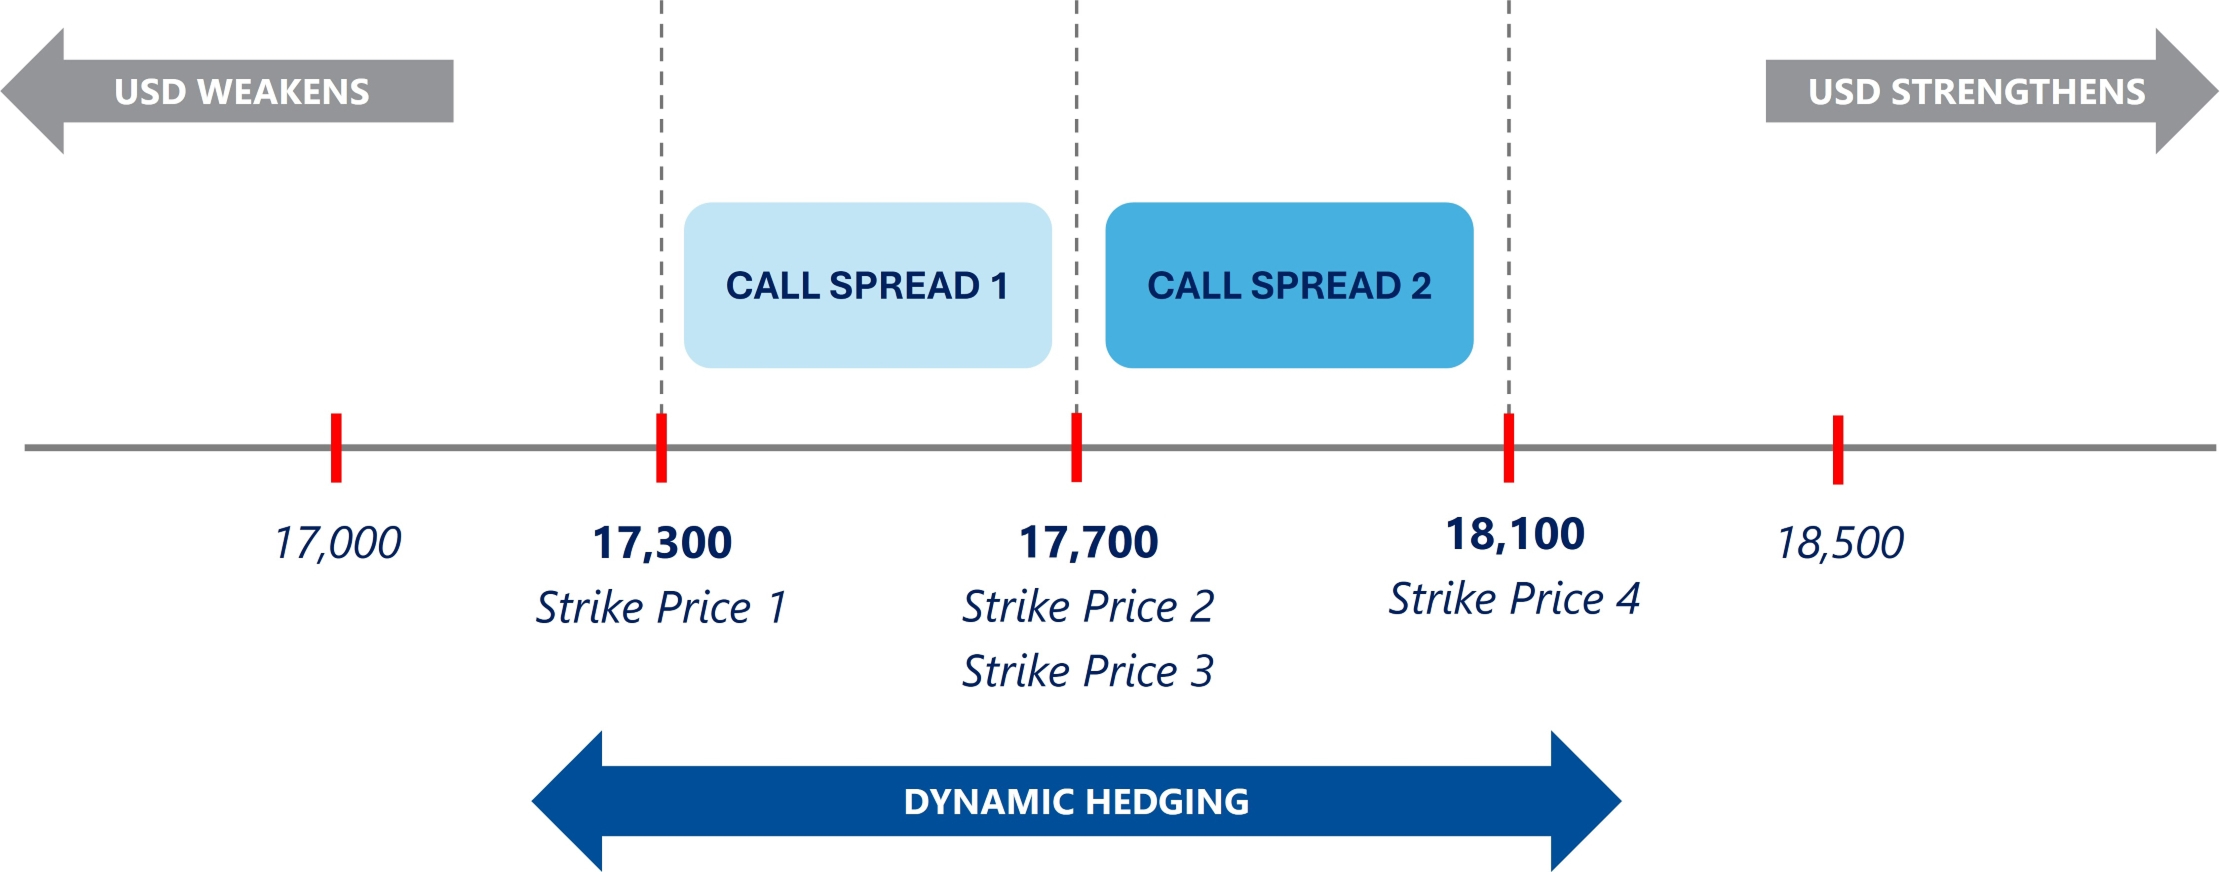
- Extends the protection range as market rates move higher.
- Allows the hedging strategy to adapt to changing market conditions while still using the same transaction underlying.
Fees
The buyer of the Call Spread Option is required to pay a premium, which is determined based on factors including the transaction terms and prevailing market conditions.Frequently Asked Questions
Who is Call Spread Option suitable for?

Call Spread Option is suitable for businesses that wish to manage foreign exchange risk (purchase of foreign currency) while potentially reducing the upfront premium compared to a standalone FX Options. It may be appropriate for Customers who are comfortable with exchange rate benefits being limited to a predefined range.
Who is eligible to enter into a Call Spread Option transaction?
Call Spread Option is a structured product and is only available to Customers who meet the applicable regulatory requirements and the Bank’s eligibility criteria. This includes, among others:
- Qualifying as a Professional Customer in accordance with applicable regulations.
- Completing the Bank’s suitability assessment and having an appropriate risk profile for the product.
- Executing the required agreements and other documents required by the Bank.
How is a Call Spread Option different from a standard FX Options?
A Call Spread Option combines the purchase and sale of two FX Options with different strike rates but the same maturity date. While this structure may reduce the upfront premium, the exchange rate benefit is capped at the upper strike rate.
Is premium payable for a Call Spread Option?
Yes. The buyer of the Call Spread Option is required to pay a premium. The premium is determined based on factors including the transaction terms and prevailing market conditions. The premium is typically quoted as a percentage of the transaction notional.
What is Dynamic Hedging?
Dynamic Hedging is a feature that allows Customers, subject to applicable regulations, to establish a new Call Spread Option as market conditions change. This creates a new protection range and enables the hedging strategy to be adjusted over time.
Will another premium be required to be paid if the Customer enter into Dynamic Hedging?
Yes. Each Dynamic Hedging transaction constitutes a new Call Spread Option. A new premium will be payable for each new transaction based on prevailing market conditions at the time it is entered into.
What happens if exchange rates move above the upper strike?
Once the exchange rate moves above the upper strike, the exchange rate benefit under the existing Call Spread Option is capped. Subject to applicable regulations and market conditions, Customers may choose to establish a new Call Spread Option through Dynamic Hedging to create a new protection range.
What happens if exchange rates move after the Customer purchase a Call Spread Option?
Changes in exchange rates, market volatility, interest rates, and the remaining time to expiry may affect the market value of the Call Spread Option.
Can I terminate the Call Spread Option before maturity?
Yes. A Call Spread Option may be terminated or unwound before maturity, subject to the Bank s agreement and prevailing market conditions. Early termination may result in a loss and may incur applicable costs.
As Call Spread Option is generally intended to be held until maturity, early termination is typically not recommended unless there is a change in the Customer's hedging requirements or other exceptional circumstances. Customer's should carefully consider the financial implications before requesting an early termination.
What risks should I consider before entering into a Call Spread Option?
Customers should consider the risks associated with Call Spread Options, including market risk, credit risk, liquidity risk and compliance risk. Customers should ensure they understand the product features, benefits and risks before entering into the transaction.
Can Call Spread Option be customised?
Yes. Subject to the Bank's approval and prevailing market conditions, key transaction terms such as the currency pair, notional amount, strike rates and maturity date can be tailored to meet specific hedging requirements.
You may also like
FX Options
Manage foreign exchange risk while maintaining flexibility.
Domestic Non-Deliverable Forward
Manage FX risk with greater certainty through IDR-settled hedging.
Par Forward
FX hedging tool for customers with recurring foreign currency payments or receipts over a set period.
We are here to help
Kami menggunakan cookie untuk meningkatkan dan menyesuaikan pengalaman penelusuran Anda. Anda dianggap telah menyetujui kebijakan cookie kami jika Anda melanjutkan untuk menjelajahi situs kami.

