


Financial Supply Chain Management
Sustainable Trade Finance
Sustainability Report

-
you are in Wholesale Banking

For Individuals
Personal BankingWealth BankingPrivilege BankingFor Companies
Wholesale BankingINDUSTRY INSIGHTSAbout UOB
ABOUT USUOB FinLaB
UOB FinLab

Overview
Interest Rate Swap (IRS) is a derivative transaction that enables counterparties to exchange interest payment obligations based on the same principal amount in the same currency.An Interest Rate Swap may help manage exposure to interest rate fluctuations by converting floating rate obligations into fixed-rate obligations, or vice versa, depending on financial objectives and market conditions.
Benefits
Interest rate risk management
Helps manage exposure to interest rate movements.
Cash flow certainty
Supports more predictable interest cash flows.
Flexible transaction terms
tructured around financing and hedging needs
Competitive pricing
Access competitive pricing from UOB Indonesia.
Treasury expertise
Benefit from UOB Indonesia’s treasury expertise.
Features
-
Key Features
-
Details
| Key Features | Details |
| Available Currencies | Available for selected foreign currencies, including AUD, CAD, CHF, CNH, EUR, GBP, HKD, IDR, JPY, NZD, SEK, SGD, and USD, subject to prevailing market conditions and the Bank’s approval. |
| Flexible Tenor | Available with a tenor up to 10 (ten) years, subject to applicable regulations and the Bank’s approval. |
| Interest Rate Hedging | Designed to help manage interest rate risk arising from financing or investments. |
| Flexible Interest Rate Structure | Exchange fixed and floating interest payment obligations based on financing or investment objectives. |
| Customisable Terms | Notional amount, amortisation, tenor, payment frequency, reference rate, and fixed rate are mutually agreed to suit specific requirements. |
| No Principal Exchange | The notional principal amount serves solely as the basis for calculating interest payments and is not exchanged. |
| Transaction Requirements | • Have an FX and Derivative Limit facility with the Bank. • Having an account with the Bank. • Sign agreement and/or other documents required by the Bank. • Provide transaction supporting document. |
| Key Features |
| Available Currencies |
| Flexible Tenor |
| Interest Rate Hedging |
| Flexible Interest Rate Structure |
| Customisable Terms |
| No Principal Exchange |
| Transaction Requirements |
Product risk
-
Risks
-
Details
| Risks | Details |
| Market Risk | Changes in market interest rates may affect the market value of the Interest Rate Swap during its tenor. |
| Credit Risk | Risk that arises if the Bank is unable to fulfil its contractual obligations under the Interest Rate Swap transaction, which may affect settlement of the transaction. |
| Liquidity Risk | Depending on market conditions, early termination, cancellation, amendment or unwind of the Interest Rate Swap may not always be available and may result in additional costs or a gain or loss based on the prevailing market value of the transaction. |
| Compliance Risk | Changes in applicable laws and regulations, including amendments to provisions and policies issued by the Government, Bank Indonesia and / or the Financial Services Authority (OJK), may affect the availability, structure, pricing, settlement or continuation of the Interest Rate Swap transaction. |
| Risks |
| Market Risk |
| Credit Risk |
| Liquidity Risk |
| Compliance Risk |
How it works
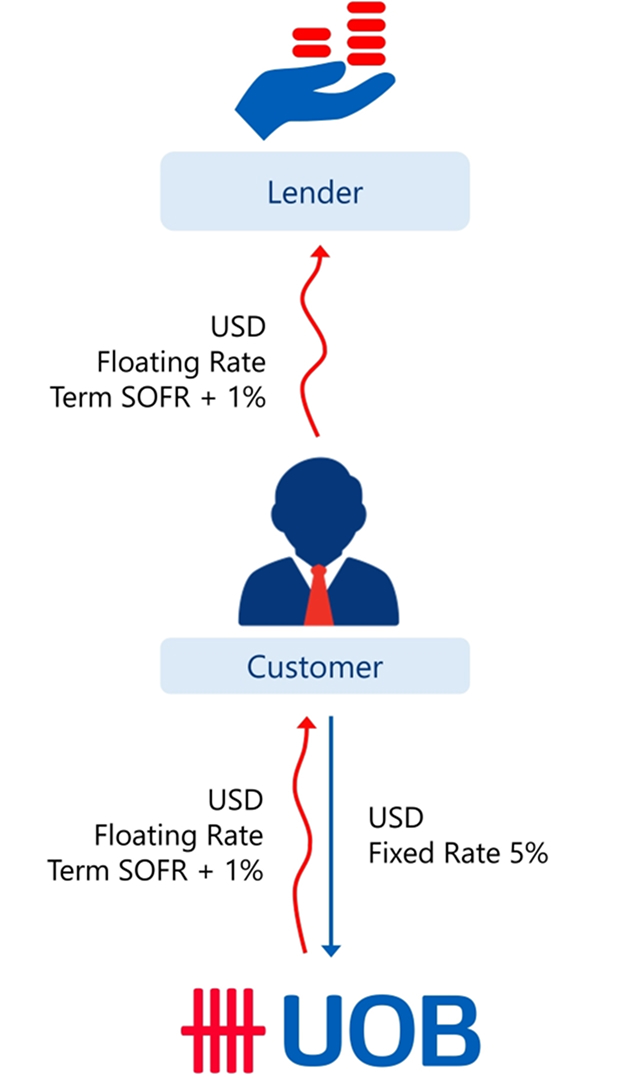
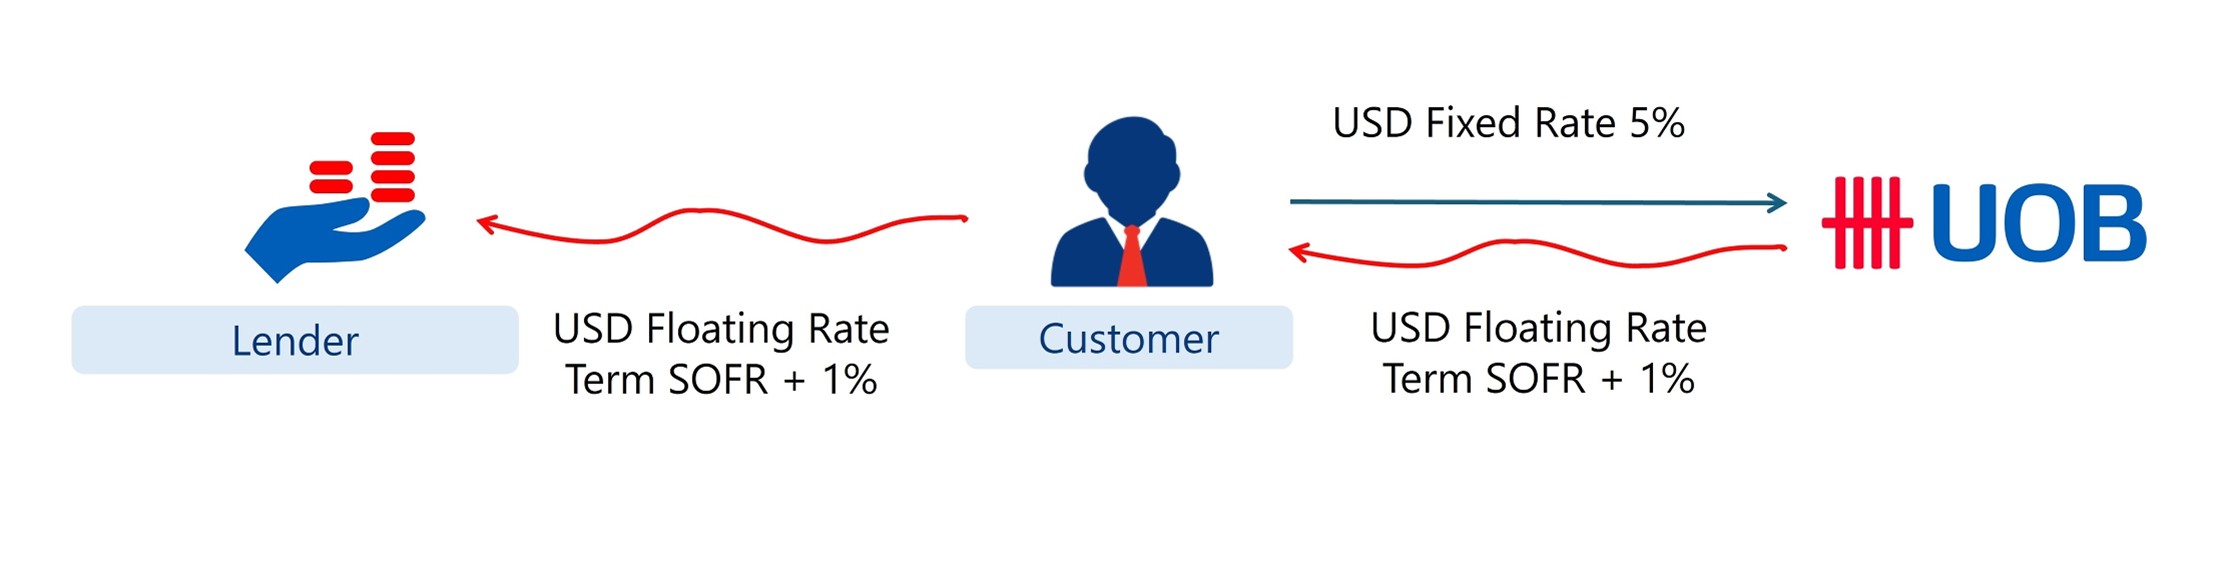
In a typical Interest Rate Swap, one party pays a fixed interest rate while receiving a floating interest rate, and the other party pays a floating interest rate while receiving a fixed interest rate. Interest payments are calculated based on an agreed notional principal amount, which is not exchanged between the parties.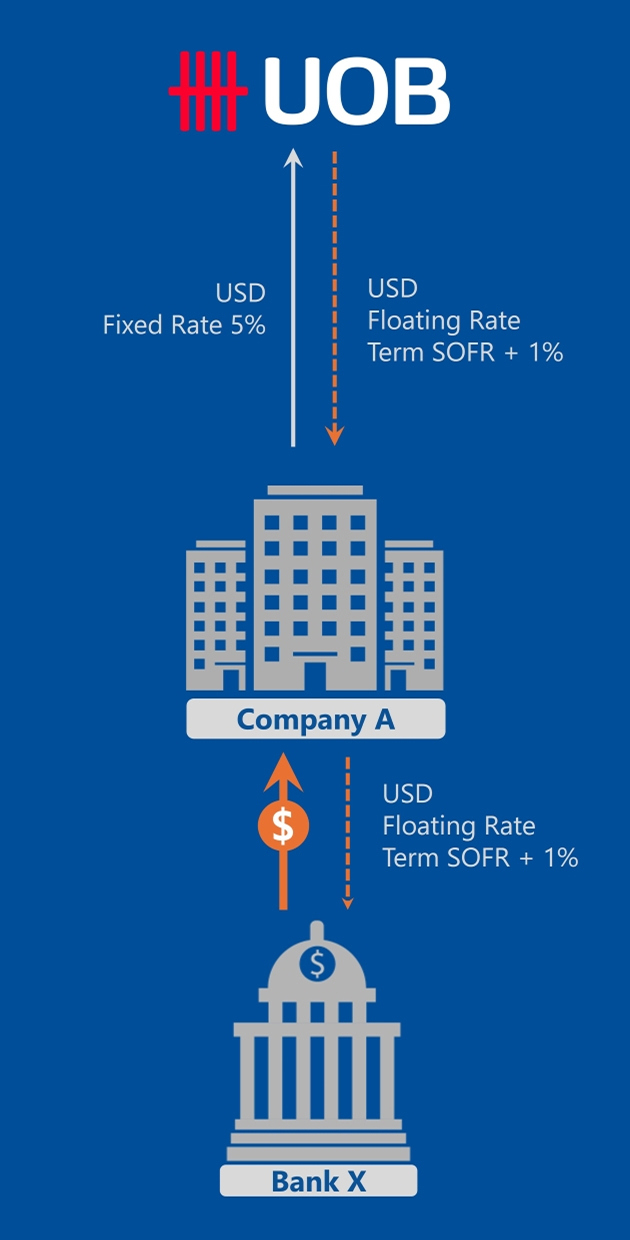
Scenario
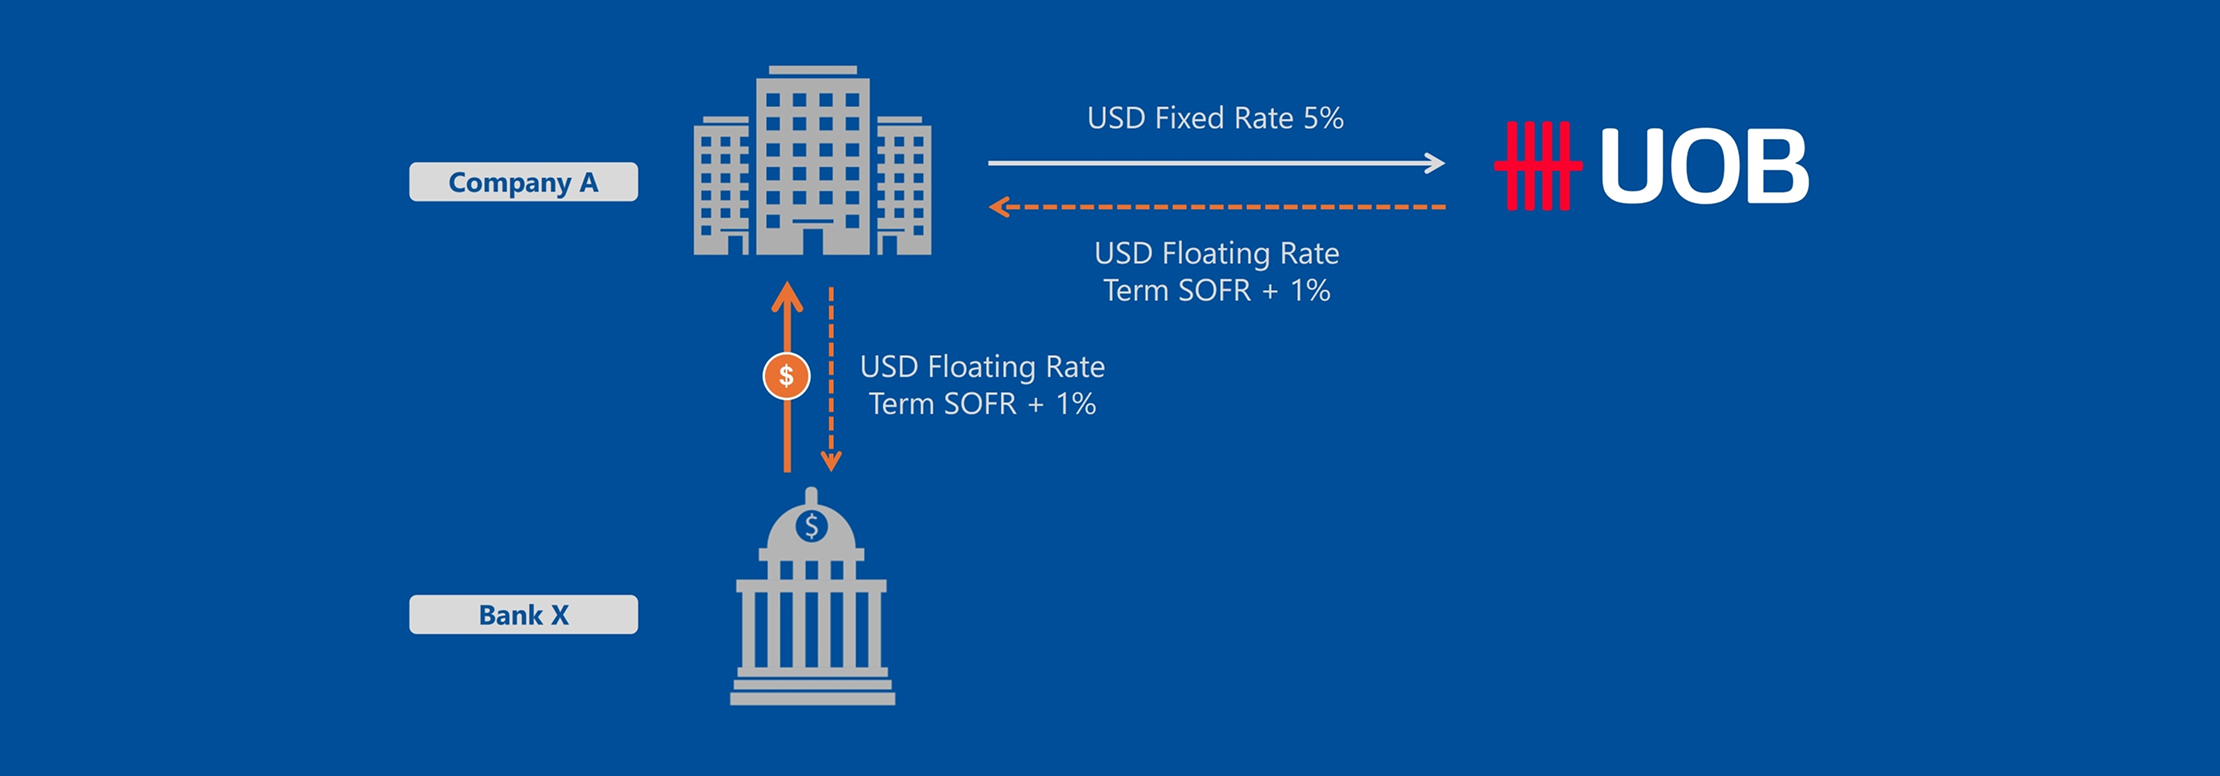
A company has a USD floating-rate loan from another financial institution with an interest rate of Term SOFR + 1%. The company expects market interest rates to rise and wishes to reduce the uncertainty of future interest payments.- Pays a fixed interest rate of 5% to UOB Indonesia.
- Receives a floating interest rate based on Term SOFR + 1% from UOB Indonesia.
Fees
There are no upfront transaction fees charged by the Bank under normal circumstances for entering into an Interest Rate Swap.Frequently asked questions
What is an Interest Rate Swap?

An Interest Rate Swap (IRS) is a derivative transaction where two parties agree to exchange interest payment obligations, typically between fixed and floating interest rates, based on an agreed notional principal amount. The notional principal itself is not exchanged.
Who can enter into an Interest Rate Swap?
Interest Rate Swaps may be suitable for corporate Customers who wish to manage exposure to interest rate movements in relation to their financing or investments, subject to the Bank's eligibility requirements and applicable regulations. Customers are required to satisfy the specific regulatory criteria, including maintaining a banking relationship with UOB Indonesia and providing supporting documents for the Bank's assessment prior to entering into the transaction.
Can an Interest Rate Swap be customised?
Yes. The notional amount, amortisation, tenor, payment frequency, reference rate, and fixed interest rate are agreed between the Customer and the Bank to meet specific requirements.
What reference interest rates can be used?
The floating interest rate is based on an agreed reference rate, such as IndONIA, SOFR, or another benchmark accepted by the parties, depending on the currency and market convention.
What documents are required before entering into an Interest Rate Swap?
Customers are required to maintain the necessary banking relationship and complete the documentation required by the Bank before transacting, including any applicable agreements and supporting documents.
How do changes in market interest rates affect an Interest Rate Swap?
Changes in market interest rates do not alter the agreed terms of an existing Interest Rate Swap. However, they may affect the transactions market value.
Can the terms of an Interest Rate Swap be amended after execution?
Changes to the agreed terms may be possible subject to mutual agreement between the Customer and the Bank. Such changes may be subject to prevailing market conditions and could result in additional costs.
You may also like
Cross Currency Swap
Tailored solutions to help manage foreign currency and interest rate exposures.
Call Spread Option
Manage foreign exchange exposure with a flexible and cost-efficient hedging solution.
FX Options
Manage foreign exchange risk while maintaining flexibility.
We are here to help
Kami menggunakan cookie untuk meningkatkan dan menyesuaikan pengalaman penelusuran Anda. Anda dianggap telah menyetujui kebijakan cookie kami jika Anda melanjutkan untuk menjelajahi situs kami.

